
 - https://sketchapp.com --%3e %3ctitle%3eIcon/search%3c/title%3e %3cdesc%3eCreated with Sketch.%3c/desc%3e %3cg id='Icon/search' stroke='none' stroke-width='1' fill='none' fill-rule='evenodd' stroke-linecap='round' stroke-linejoin='round'%3e %3ccircle id='Oval' stroke='%23252525' cx='10.5145111' cy='10.5145111' r='6.99455261'%3e%3c/circle%3e %3cpath d='M15.4908752%2c15.4908752 L20.5515137%2c20.5515137' id='Line' stroke='%23252525'%3e%3c/path%3e %3c/g%3e%3c/svg%3e)


Melbourne property market news - key takeaways
- Values continue to fall: Melbourne dwelling values declined -1.1 per cent in August 2026 and -4.7 per cent over the year, with the Melbourne property market now sitting -6.8 per cent below its March 2022 peak.
- Stock building, listings tight at source: Total listings rose +14.2 per cent year on year as homes take longer to sell, even as new listings fell -13.7 per cent, leaving buyers with more choice but sellers with more competition.
- Auction conditions favour buyers: Melbourne returned a clearance rate of 54.6 per cent from 656 auctions in the week ending 6 September 2026, a soft result that gives buyers meaningful room to negotiate.
- Rents rising, yields improving: Annual rent growth of +5.0 per cent has pushed Melbourne's gross yield to 4.0 per cent, above the combined capitals average of 3.6 per cent, as values ease while rents keep climbing.
- Rate rise on the horizon: All four major banks expect the RBA cash rate to rise to 4.60 per cent before year end, adding further pressure on borrowing capacity at a time when Melbourne house prices already sit above $920,000.

Get a free property value estimate
Find out how much your property is worth in today’s market.
Melbourne property price movements
Melbourne's property market recorded broad-based price falls in August 2026, extending a decline that has now run for several consecutive months. The city is one of the softer-performing capitals nationally, with pressure spread across both houses and units.
Melbourne property prices - August 2026
Melbourne home values fell -1.1 per cent over the month in August 2026, adding to a quarterly decline of -3.9 per cent and an annual fall of -4.7 per cent. The annual figure confirms the pullback has been sustained across the full year to date.
| Property type | Current median price | Monthly change | Quarterly change | Annual change |
|---|---|---|---|---|
| All Melbourne dwellings | $786,718 | -1.1% | -3.9% | -4.7% |
Source: Cotality
The median home value in Melbourne now sits at $786,718, down around $8,764 on the prior month. Values remain -6.8 per cent below their March 2022 peak, meaning the gap to that record high has widened further through the August result.
House prices in Melbourne
Melbourne house prices fell -1.4 per cent over the month in August 2026, with the quarterly and annual measures also in negative territory at -4.6 per cent and -5.7 per cent respectively. The annual house decline is steeper than the broader all-dwellings figure, reflecting the weight houses carry in the overall index.
| Property type | Current median price | Monthly change | Quarterly change | Annual change |
|---|---|---|---|---|
| Melbourne houses | $920,432 | -1.4% | -4.6% | -5.7% |
Source: Cotality
The median house value of $920,432 represents a fall of around $13,046 compared with the prior month. Over the full year, the -5.7 per cent annual decline on houses is notably steeper than the -2.5 per cent recorded for units, pointing to houses absorbing a greater share of the market's adjustment pressure.
Unit prices in Melbourne
Melbourne unit prices eased -0.5 per cent over the month in August 2026, a more resilient outcome than the broader market, with a quarterly fall of -2.4 per cent and an annual decline of -2.5 per cent. Unit prices have held up considerably better than houses across every timeframe measured.
| Property type | Current median price | Monthly change | Quarterly change | Annual change |
|---|---|---|---|---|
| Melbourne units | $629,054 | -0.5% | -2.4% | -2.5% |
Source: Cotality
At a median of $629,054, unit values slipped by around $3,161 over the month. The gap between the annual unit decline of -2.5 per cent and the annual house decline of -5.7 per cent is more than 3 percentage points, a difference large enough to be meaningful rather than statistical noise, and one that suggests the unit segment is finding a degree of support that the house market is not.
Melbourne property market forecasts 2026
Australia's Big Four banks publish dwelling price forecasts each year as part of their economic research divisions' outlook work. For Melbourne in 2026, the picture is notably consistent: every major bank expects values to fall further over the calendar year, though the scale of the projected declines varies considerably.
- CBA predicts Melbourne property prices to fall -7.0 per cent over 2026.
- Westpac predicts Melbourne property prices to fall -4.0 per cent over 2026.
- NAB predicts Melbourne property prices to fall -9.0 per cent over 2026.
- ANZ predicts Melbourne property prices to fall -9.2 per cent over 2026.
The forecast spread runs from -4.0 per cent (Westpac, the least severe of the four) to -9.2 per cent (ANZ, at the other end). CBA's -7.0 per cent sits closer to the sharper end of the range, while NAB's -9.0 per cent clusters tightly with ANZ. Westpac stands apart as the sole bank projecting a relatively contained decline, a meaningful gap from its peers when considering Melbourne property market predictions for the year ahead.
RBA cash rate forecast 2026-2027
The RBA cash rate currently sits at 4.35 per cent, a level that already reflects a substantial tightening cycle. All four major banks expect the next move to be a rise, though they differ on timing, with NAB forecasting the earliest move and the others pointing to later in the year.
- ANZ expects the next cash-rate move to be a 25 basis point rise in November 2026, bringing the cash rate to 4.60 per cent.
- CBA expects the next cash-rate move to be a 25 basis point rise in November 2026, bringing the cash rate to 4.60 per cent.
- NAB expects the next cash-rate move to be a 25 basis point rise in September 2026, forecasting a risk of another rise in November 2026 to bring the cash rate to 4.60 per cent.
- Westpac expects the next cash-rate move to be a 25 basis point rise in November 2026, bringing the cash rate to 4.60 per cent.
Sally Tindall, Data Insights Director at Canstar said of the rate outlook:"The economic narrative has taken a U-turn in the space of just a couple of days."
Tindall's observation captures how quickly the rate environment can shift, and for Melbourne borrowers that volatility carries real weight. With the cash rate already at 4.35 per cent and another rise potentially weeks away, the path for affordability in the near term remains under pressure.
What this means for the Melbourne market
A cash rate at 4.35 per cent, and potentially heading to 4.60 per cent before the year is out, compresses borrowing capacity for Melbourne buyers at a time when the median house price sits at $920,432. That combination of elevated rates and high entry prices is a material constraint, particularly for buyers stretching to the top of what they can borrow.
The rate outlook also helps explain why the Big Four's Melbourne forecasts are skewed toward the sharper end of the national decline range. Higher rates reduce the pool of buyers who can comfortably service a large Melbourne mortgage, which keeps demand soft and gives sellers less room on price. Units, with a median of $629,054 and comparatively lower borrowing requirements, are less exposed to that pressure than houses, though the bank forecasts cover dwellings broadly and do not distinguish between the two segments.
Helpful resource: Our simple guide to tracking market trends and data will walk you through everything you need to know to be able to read the market and make a smarter selling decision.
Melbourne house prices graphs and charts
Melbourne's house price growth over the last 5 years has shifted sharply in recent months, with dwelling values falling -1.1 per cent in August 2026, -3.9 per cent over the quarter, and -4.7 per cent over the year, according to Cotality's latest figures, placing the current dwelling median at $786,718.
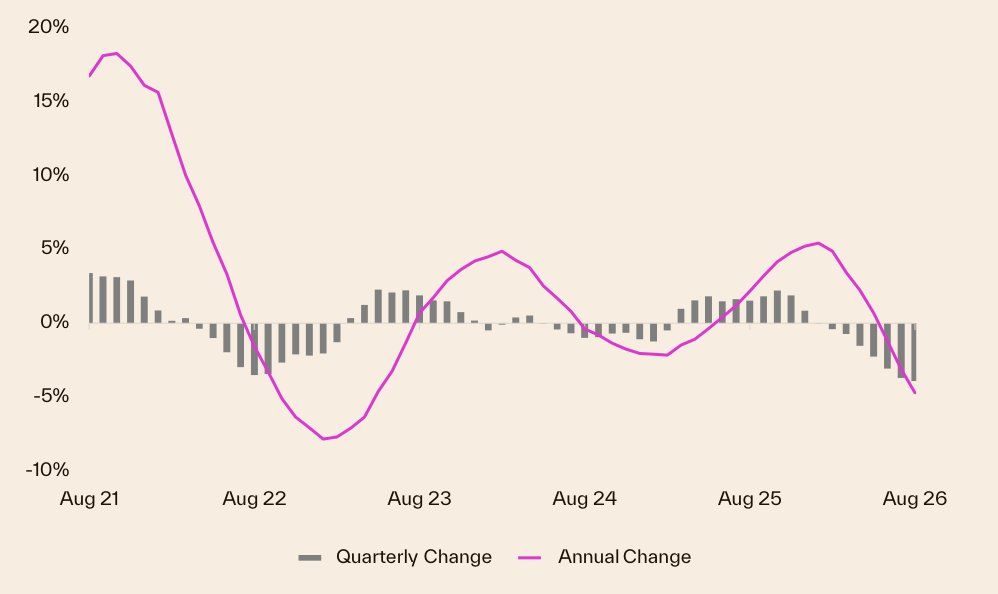
The five-year picture captures a market that ran hard through the post-pandemic period before the RBA's rate-tightening cycle, which lifted the cash rate to 4.35 per cent, began to press on buyer capacity. With the cash rate at its highest point in over a decade and all four major banks anticipating a further 25 basis point rise, the quarterly pace of decline has gathered speed through 2026, reflecting tighter borrowing conditions and a broad pull-back in buyer confidence as business conditions turn softer.
Melbourne property 30 year property price graph
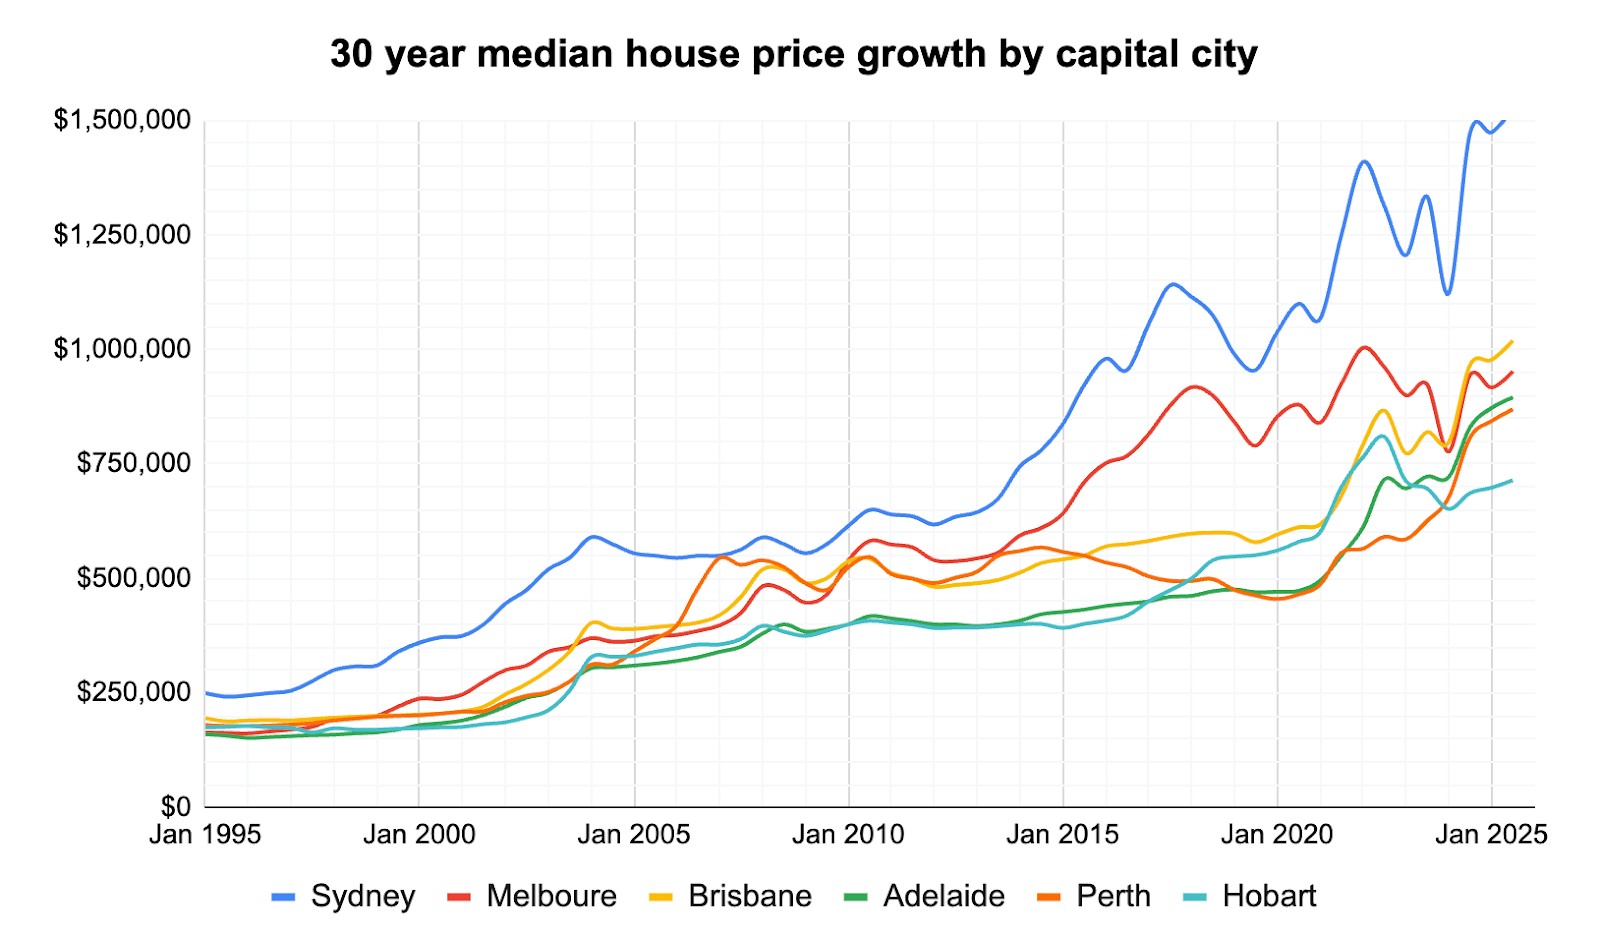
This recent “slow grind” back toward prior highs sits alongside Melbourne property prices growth over the last 10 years, where strong long-run gains were driven by falling interest rates, population growth and constrained supply that together pushed the median much higher; OpenAgent’s historical review shows Melbourne’s median house price rising to roughly $1.1 million by 2025, reflecting that decade-plus of solid appreciation.
Over the past 30 years, Melbourne has repeatedly moved through booms and corrections, and today, homeowners are more cautious while still supported by tight rental markets and ongoing population inflows; supply shortfalls and construction constraints mean demand pressures remain, even as higher borrowing costs temper how fast prices can climb.
Melbourne selling statistics
Melbourne's selling conditions in August 2026 reflect a market where buyers have more room to move than they have had in recent years. Stock levels are elevated, properties are taking longer to sell, and sellers are accepting greater discounts from their initial asking prices than they were twelve months ago.
Want to know what your own property is worth? Get a free value estimate for your address.
Melbourne sales volume and days on market
Melbourne sales volume slipped -0.6 per cent year on year in August 2026, while properties took 43 days on market to sell, up from 30 days a year earlier. That 13-day extension in selling time is a concrete sign that buyer urgency has eased considerably.
| Melbourne sales volume | Melbourne days on market |
|---|---|
| -0.6% Change from 12mo ago | 43 days 30 days 12 mo ago |
Source: Cotality
Melbourne's sales volume decline of -0.6 per cent compares favourably with both the combined capitals (-5.2 per cent) and the national figure (-2.7 per cent), suggesting transaction activity here has held up better than the broader trend. Days on market tell a different story: at 43 days, Melbourne properties are sitting on the market longer than both the combined capitals average of 37 days and the national average of 39 days, meaning sellers here are waiting notably longer to find a buyer than their counterparts elsewhere.
Melbourne new and total listings
New listings fell -13.7 per cent year on year, while total listings rose +14.2 per cent over the same period. Those two figures moving in opposite directions tell a clear story about how the market has shifted.
| Melbourne new listings | Melbourne total listings |
|---|---|
| -13.7% Change from 12mo ago | +14.2% Change from 12mo ago |
Source: Cotality
Fewer sellers are choosing to list, yet the pool of available properties keeps growing because homes are taking longer to sell and unsold stock is accumulating. For buyers, this means more choice and less pressure to act quickly. For sellers, it means more competition from other properties already on the market.
Melbourne vendor discount and auction clearance rates
Vendor discount measures the gap between a property's initial asking price and its eventual sale price, expressed as a percentage. Auction clearance rate measures the share of properties that sell at or before auction, out of those scheduled to go under the hammer. Together they offer a read on how much negotiating room buyers have and how confident sellers can be about achieving their price on auction day.
Melbourne vendor discount
| August 2026 | August 2025 | |
|---|---|---|
| Melbourne median vendor discount | -3.9% | -3.0% |
Source: Cotality
Melbourne's vendor discount widened to -3.9 per cent in August 2026, compared with -3.0 per cent a year earlier. Sellers are accepting offers roughly a full percentage point further below their asking price than they were twelve months ago, a shift that reflects the increased competition from accumulated stock and the longer time properties are spending on the market.
Melbourne auction clearance rates
| Melbourne | 6 Sep 2026 |
|---|---|
| Total Auctions | 656 |
| Sold | 358 |
| Withdrawn | 101 |
| Passed in | 197 |
| Clearance Rate | 54.6% |
Source: Cotality
Melbourne returned a clearance rate of 54.6 per cent from 656 auctions in the week ending 6 September 2026, with 197 properties passed in and a further 101 withdrawn.
A rate in the mid-fifties sits in clearly buyer-favourable territory by historical standards, well below the long-run decade average of around 64 per cent. The volume of withdrawals, roughly 15 per cent of all scheduled auctions, also points to a degree of price tension, with some vendors opting to defer rather than accept offers below their expectations on the day.
Thinking of selling? Compare top-performing local agents in your suburb to find the right fit for your sale.
Get a deeper insight into how Melbourne sellers are faring in 2026 and what could be on the horizon for the year ahead with some of our latest articles.




Melbourne property investing
Melbourne's property market is in a period of falling values, but the rental side of the ledger tells a different story. Rents have continued to climb over the past year, and yields have held at a level that places Melbourne in a competitive position relative to some of Australia's largest capital markets.
Helpful resource: Estimate the capital gains tax on a sale with our free calculator.
Melbourne rental market
The table below covers annual rent growth, gross rental yield, and the split between houses and units for Melbourne alongside other Australian capital cities and national aggregates. These figures give investors and renters alike a clear read on where Melbourne sits in the broader rental picture.
| Location | Rental rates | Rental yield | Annual change in rents, houses | Annual change in rents, units |
|---|---|---|---|---|
| National | 5.7% | 3.8% | NA | NA |
| Combined Capitals | 5.7% | 3.6% | NA | NA |
| Combined Regional | 5.8% | 4.3% | NA | NA |
| Sydney | 4.8% | 3.3% | 5.3% | 3.9% |
| Melbourne | 5.0% | 4.0% | 5.1% | 4.9% |
| Brisbane | 6.4% | 3.4% | 6.7% | 5.6% |
| Adelaide | 5.8% | 3.6% | 5.8% | 6.0% |
| Perth | 8.0% | 3.9% | 8.1% | 7.4% |
| Hobart | 7.9% | 4.4% | 8.5% | 6.0% |
| Darwin | 11.4% | 6.3% | 12.0% | 10.5% |
| Canberra | 3.2% | 4.3% | 4.0% | 1.4% |
Source: Cotality
Melbourne recorded annual rent growth of +5.0 per cent in the year to August 2026, with houses and units moving at broadly the same pace, +5.1 per cent and +4.9 per cent respectively. At 4.0 per cent, Melbourne's gross yield sits above the combined capitals average of 3.6 per cent and above Sydney's 3.3 per cent, reflecting the fact that property values in Melbourne have eased meaningfully while rents have kept climbing.
Melbourne vacancy rates
The vacancy rate is the share of rental properties sitting empty at any given time. A low rate points to strong rental demand and limited choice for tenants, while a higher rate gives renters more options and can place downward pressure on rents. SQM data shows the Melbourne vacancy rate and its movement over the past year.
| Location | Aug 2026 vacancy rates | Aug 2026 vacancies | Aug 2025 vacancy rates | Aug 2025 vacancies |
|---|---|---|---|---|
| National | 1.3% | 41,039 | 1.2% | 37,742 |
| Sydney | 1.7% | 12,821 | 1.4% | 10,211 |
| Melbourne | 1.8% | 9,534 | 1.8% | 9,620 |
| Brisbane | 0.9% | 3,090 | 1.0% | 3,423 |
| Adelaide | 0.6% | 1,019 | 0.8% | 1,257 |
| Perth | 0.6% | 1,192 | 0.7% | 1,389 |
| Hobart | 0.6% | 158 | 0.5% | 144 |
| Darwin | 0.4% | 94 | 0.5% | 134 |
| Canberra | 2.1% | 1,264 | 1.6% | 978 |
Source: SQM Research
Melbourne's vacancy rate has held essentially flat at 1.8 per cent, with the actual number of vacant properties edging slightly lower from 9,620 a year ago to 9,534. At 1.8 per cent, Melbourne sits above the national rate of 1.3 per cent, placing it among the looser capital city rental markets alongside Sydney and Canberra, while markets such as Adelaide, Perth and Brisbane remain considerably tighter.
Louis Christopher, Managing Director at SQM Research said in the latest rental market report:
"The national vacancy rate is 1.3%, but that hides a market moving in two directions. Sydney has 26% more vacancies than a year ago and Canberra 29% more, while Brisbane, Perth, Adelaide and Darwin have fewer than they did last August."
Melbourne fits the pattern described above, sitting on the looser side of the national divide alongside Sydney and Canberra. With vacancies little changed year on year and the vacancy rate above the national average, rental demand in Melbourne is not generating the same upward pressure on rents seen in the tighter markets.
For investors, the flat vacancy trend suggests the Melbourne rental market is stable rather than tightening, and the yield of 4.0 per cent reflects an improving income return as values have pulled back while rents continue to edge higher.
Highest growth areas in Melbourne
Melbourne's strongest-performing SA3 regions in August 2026 were concentrated in the city's outer west and north-west corridors, with affordability playing a clear role in shaping which areas held their ground. The table below ranks the top 10 Statistical Area Level 3 (SA3) regions across Greater Melbourne by annual percentage change. Each SA3 is an ABS-defined geographic unit that typically covers several adjacent suburbs.
| Rank | SA3 Name | SA4 Name | Median Value | Annual % Change |
|---|---|---|---|---|
| 1 | Sunbury | North West | $725,708 | 2.7% |
| 2 | Brimbank | West | $712,104 | 1.5% |
| 3 | Maribyrnong | West | $673,786 | 1.1% |
| 4 | Casey - South | South East | $786,781 | 0.7% |
| 5 | Melton - Bacchus Marsh | West | $658,943 | 0.0% |
| 6 | Keilor | North West | $1,016,243 | -0.5% |
| 7 | Tullamarine - Broadmeadows | North West | $708,296 | -0.8% |
| 8 | Wyndham | West | $685,275 | -0.9% |
| 9 | Melbourne City | Inner | $509,747 | -0.9% |
| 10 | Casey - North | South East | $828,562 | -0.9% |
Source: Cotality
Highlights for Melbourne’s high growth areas
- Sunbury: Ranked #1 across Greater Melbourne with annual growth of +2.7 per cent and a median value of $725,708, Sunbury sits in Melbourne's outer north-west and has drawn consistent interest from buyers seeking more space at a lower price point than established middle-ring suburbs. Suburbs such as Diggers Rest and Sunbury itself have been among the more active pockets in the region, supported by ongoing residential development and improving road and rail connections to the CBD.
- Brimbank: Ranked #2 with annual growth of +1.5 per cent and a median value of $712,104, Brimbank covers a broad band of Melbourne's inner-west that includes St Albans and Sunshine. Relative affordability compared with suburbs closer to the city centre has kept buyer interest reasonably steady, even as broader Melbourne values have pulled back.
- Maribyrnong: Ranked #3 with annual growth of +1.1 per cent and a median of $673,786, Maribyrnong encompasses established inner-west suburbs including Footscray and Yarraville. The region's proximity to the CBD and its existing community infrastructure have helped it hold up better than many parts of the city during the current period of broadly easing values.
- Outer growth corridors, south-east and west: Ranks #4 and #5, Casey - South (+0.7 per cent, $786,781) and Melton - Bacchus Marsh (0.0 per cent, $658,943), each represent Melbourne's expanding outer fringe, where new housing estates continue to draw first-home buyers and growing families. Casey - South includes established suburbs such as Cranbourne and Clyde North, while Melton - Bacchus Marsh covers a large corridor stretching west to Bacchus Marsh and Caroline Springs, where land supply remains a key factor in keeping median values among the lowest in the top 10.
- North-west mid-ring and outer corridors: Ranks #6 through #8, Keilor (-0.5 per cent, $1,016,243), Tullamarine - Broadmeadows (-0.8 per cent, $708,296) and Wyndham (-0.9 per cent, $685,275), recorded modest annual declines but remain in Melbourne's upper half of the growth table by that measure. Keilor's median of $1,016,243 is the highest in this group, reflecting suburbs such as Strathmore and Niddrie that sit closer to the city, while Wyndham suburbs including Point Cook and Tarneit represent a large and still-growing corridor in Melbourne's south-west.
Thinking of selling or investing in Melbourne? Compare local agents or get a free property report with OpenAgent.
View agent & property tools

Our powerful property tools


 - https://sketch.com --%3e %3ctitle%3eicons / icon-chevron-down%3c/title%3e %3cdesc%3eCreated with Sketch.%3c/desc%3e %3cg id='icons-/-icon-chevron-down' stroke='none' stroke-width='1' fill='none' fill-rule='evenodd'%3e %3crect id='Icon-container' x='0' y='0' width='24' height='24'%3e%3c/rect%3e %3cpolygon id='Shape' fill='%2300AB55' points='12 14.3357864 5.20710678 7.54289322 3.79289322 8.95710678 12 17.1642136 20.2071068 8.95710678 18.7928932 7.54289322'%3e%3c/polygon%3e %3c/g%3e%3c/svg%3e)